CPF Retirement Sum — BRS, FRS and ERS
What you set aside at 55, all three levels, and the figure for every cohort — from CPF Board’s own tables
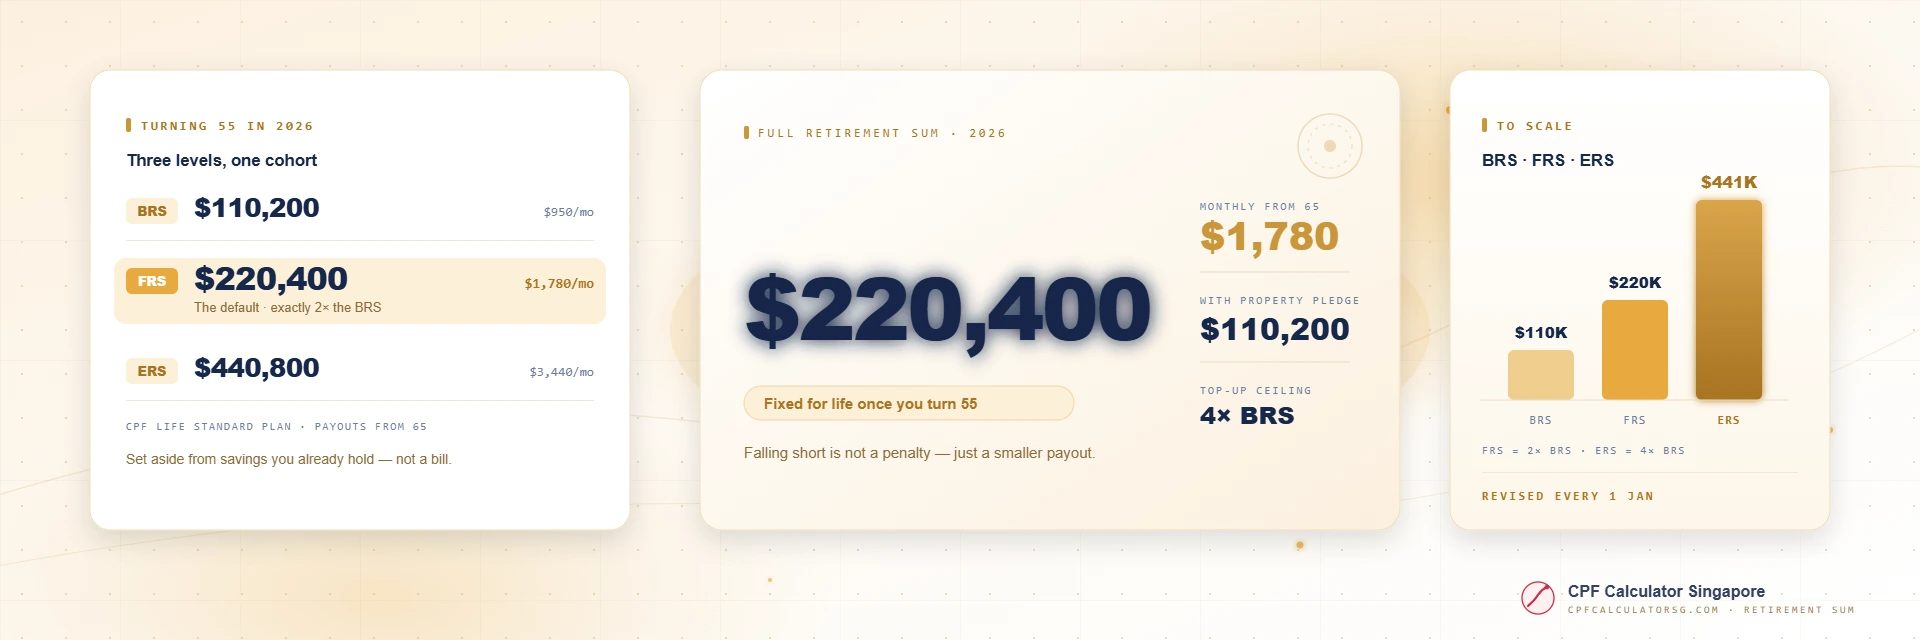
The Three Retirement Sums
Amounts for the current cohort, with the monthly income each buysOne figure became three in 2016. Which one you are measured against depends on whether you pledge a property and whether you choose to top up; the arithmetic between them is fixed by CPF Board, not chosen by you. The Full Retirement Sum is exactly twice the Basic, and the Enhanced is a multiple of the Basic set each January.
| Retirement sum | Short name | Amount to set aside at 55 in 2026 | CPF LIFE payout from 65 | Who it applies to |
|---|---|---|---|---|
| Basic Retirement Sum | BRS | $110,200 | $950 a month | You own a property and pledge it to CPF |
| Full Retirement Sum | FRS | $220,400 | $1,780 a month | The default, and the figure the old “minimum sum” became |
| Enhanced Retirement Sum | ERS | $440,800 | $3,440 a month | The ceiling if you choose to top up for a larger payout |
Payout basis, as published by CPF Board: CPF LIFE Standard Plan, 4% interest, payouts from age 65, for members turning 55 in 2026. The amount is what stays in the Retirement Account, not a sum you have to find in cash.
The retirement sum is set by the year you turn 55; the contribution rate that builds it is set by your age each year. Both are in the CPF contribution rate by age reference, one row per age.
The retirement sum is what the system sets aside; what members actually hold at each age is the other half of the picture. The average CPF balance by age shows both, group by group, on CPF Board's published figures.
Which Figure Applies to You
By year of 55th birthday — find your own rowYour retirement sum is set by the year you turn 55, and then it stops moving. Someone who turned 55 in 2019 is still measured against the 2019 figure however much later cohorts are asked for. That is why a bare “what is the CPF retirement sum” has no single answer: it has one answer per cohort, and they are all below.
In one line: your retirement sum is the figure for the year you turn 55 — $220,400 full, $110,200 basic for the 2026 cohort — and once set it never rises again, however much later cohorts are asked for.
| Turning 55 in… | Basic Retirement Sum (BRS) | Full Retirement Sum (FRS) | Enhanced Retirement Sum (ERS) in force that year |
|---|---|---|---|
| 2017 | $83,000 | $166,000 | $249,000 (3× BRS) |
| 2018 | $85,500 | $171,000 | $256,500 (3× BRS) |
| 2019 | $88,000 | $176,000 | $264,000 (3× BRS) |
| 2020 | $90,500 | $181,000 | $271,500 (3× BRS) |
| 2021 | $93,000 | $186,000 | $279,000 (3× BRS) |
| 2022 | $96,000 | $192,000 | $288,000 (3× BRS) |
| 2023 | $99,400 | $198,800 | $298,200 (3× BRS) |
| 2024 | $102,900 | $205,800 | $308,700 (3× BRS) |
| 2025 | $106,500 | $213,000 | $426,000 (4× BRS) |
| 2026 | $110,200 | $220,400 | $440,800 (4× BRS) |
| 2027 | $114,100 | $228,200 | $456,400 (4× BRS) |
Read the first two columns across: they are your cohort’s figures, fixed for life at 55. Read the last column down: the ERS is the top-up ceiling in force in each calendar year for every member aged 55 and above, not a cohort figure, and it moved from 3× the BRS to 4× on 1 January 2025. Across 2017 to 2027 the Full Retirement Sum has risen about 3.2% a year. Only the BRS column is transcribed from CPF Board; the FRS is twice it and the ERS the year’s multiple of it, both derived at build time.
Before 2017: the same figure runs back to $40,000 in 1995, under its old name. CPF Board publishes the whole run — 1995 to 2027, 5.7 times over 32 years — as one continuous column. All 32 revisions are set out in the CPF Minimum Sum and its full history.
Next Year’s Figures
Already published by CPF Board| Retirement Sum | Turning 55 in 2026 | Turning 55 in 2027 | Increase |
|---|---|---|---|
| Basic Retirement Sum (BRS) | $110,200 | $114,100 | +$3,900 |
| Full Retirement Sum (FRS) | $220,400 | $228,200 | +$7,800 |
| Enhanced Retirement Sum (ERS) | $440,800 | $456,400 | +$15,600 |
The Names People Use, and What They Mean
Old terms, abbreviations, and the two that are not retirement sums at allFour different words point at the same three figures, and two more point somewhere else entirely. This table is the translation.
| If you were told… | CPF Board calls it | Amount in 2026 | What it means |
|---|---|---|---|
| “CPF minimum sum” | Full Retirement Sum | $220,400 | Renamed the Retirement Sum in 2016. Same series, same rule — see the minimum sum, 1995 to 2027 |
| “FRS” | Full Retirement Sum | $220,400 | The default figure, and twice the BRS by CPF Board’s own rule |
| “BRS” | Basic Retirement Sum | $110,200 | Applies instead of the FRS if you own a property and pledge it |
| “ERS” | Enhanced Retirement Sum | $440,800 | 4× the BRS in 2026. A ceiling on voluntary top-ups, not a requirement |
| “Retirement sum” | All three of the above | — | The family name. Which one you are measured against depends on the property pledge and on whether you top up |
| “MediSave minimum sum” | Abolished on 1 January 2016 | — | A separate rule that required a MediSave top-up before withdrawal. Removed outright; nothing replaced it |
| “Basic Healthcare Sum” | MediSave ceiling | $79,000 | Not a retirement sum. It was the Medisave Contribution Ceiling, renamed on 1 January 2016 |
The sums are one input of a whole plan. The CPF financial planning guide sequences the rest around them — contribution, allocation, housing, top-ups and the milestones.
Topping Up: the Enhanced Retirement Sum
The one figure that is not fixed to your cohortThe Enhanced Retirement Sum behaves differently from the other two, and it is the detail most often got wrong. CPF Board states that it “is not dependent on your age or the year you turn 55 years old. It increases yearly on 1 January.” It is the top-up ceiling in force during a calendar year for every member aged 55 and above, not a number attached to your cohort. In 2026 it is $440,800: 4× the Basic Retirement Sum, which is the same thing as twice the 2026 Full Retirement Sum of $220,400. The multiple moved from 3× to 4× on 1 January 2025, which is why the ceiling jumped that year.
Topping up is optional in both directions: no one is required to reach the Enhanced Retirement Sum, and money placed in the Retirement Account cannot be taken back out. What it buys is a larger lifelong payout. Whether that is the right use of the money depends on circumstances this page cannot see — it is a reference, not advice. Our guide to topping up by age sets out the trade-offs, and which account to top up first compares the options.
Common Questions
Direct answers, each traced to the same source tablesWhat is the CPF retirement sum?
It is the amount that must stay in your CPF Retirement Account from age 55 to fund a monthly income for life through CPF LIFE. For a member turning 55 in 2026 the Full Retirement Sum is $220,400. It is set aside from savings you already have, not a bill you pay.
What is the CPF Full Retirement Sum?
The Full Retirement Sum (FRS) is the default level: $220,400 for members turning 55 in 2026, rising to $228,200 for those turning 55 in 2027. CPF Board sets it at exactly twice the Basic Retirement Sum, and it pays about $1,780 a month from 65.
What is the Basic Retirement Sum?
The Basic Retirement Sum (BRS) is the lower level, $110,200 in 2026, available if you own a property and pledge it to CPF. It pays about $950 a month from 65 instead of $1,780, and lets you withdraw the difference in cash at 55.
What is the Enhanced Retirement Sum?
The Enhanced Retirement Sum (ERS) is the ceiling on voluntary top-ups: $440,800 in 2026, or 4 times the Basic Retirement Sum. Unlike the other two it is not a cohort figure. CPF Board raises it every 1 January and it applies to every member aged 55 and above.
Which year’s retirement sum applies to me?
The one for the calendar year you turn 55. Your Basic and Full Retirement Sums are fixed at that point and never rise again, however much later cohorts are asked to set aside. CPF Board publishes the figure for every cohort from 2017 onwards; the table above lists them.
What happens if I do not have the Full Retirement Sum at 55?
Nothing is forfeited and no penalty applies. Whatever is in your Retirement Account buys the payout it buys, and the shortfall simply means a smaller monthly income from 65. You can top up later, up to the Enhanced Retirement Sum in force that year.
Is the CPF minimum sum the same as the retirement sum?
Yes. CPF Board renamed the Minimum Sum the Retirement Sum in 2016 and split it into three levels. The Full Retirement Sum is the direct continuation, and CPF Board still publishes both names in one unbroken series running from 1995 to today.
How much does the CPF retirement sum go up each year?
It is revised every 1 January. The Full Retirement Sum moves from $220,400 for the 2026 cohort to $228,200 for 2027, and the Basic Retirement Sum from $110,200 to $114,100. Only the cohort reaching 55 is affected; earlier cohorts keep their own figure.